
The first steps after a collision shape the value and viability of any injury claim you file later. In Missouri, evidence can disappear within days, insurers often push for a quick recorded statement, and medical decisions in the first weeks influence both your health and your documentation. This article lays out a practical 30-day timeline. You will learn how to handle first-day essentials like the police report and emergency care, when and how to notify insurers without giving up leverage, what to do to preserve event data recorder information and store surveillance, how to track medical bills and wage loss, and how to handle early settlement pressure while staying mindful of deadlines.
First 24 Hours: Call 911, Get the Police Report Number, and Document the Scene
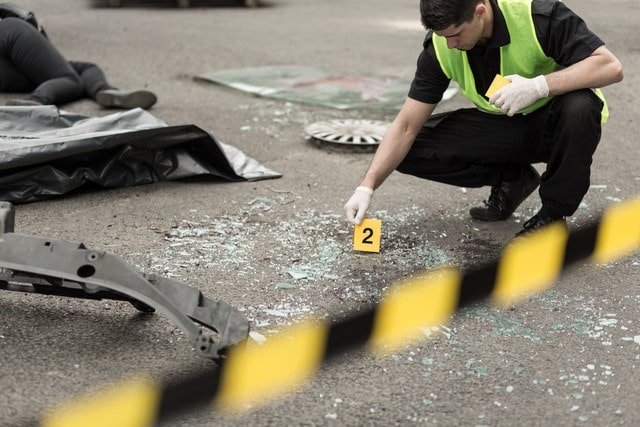
Call 911 to ensure an official crash report and EMT evaluation. Ask the officer for the incident or case number and the reporting agency. Photograph vehicle positions, skid marks, airbag deployment, traffic signals, and license plates. If you can safely do so, capture close-ups of crush damage, debris fields, and any visible injuries such as seatbelt bruising. Exchange insurance information and note the other driver’s policy number and the insurer’s claims phone line. If you are transported from the scene, later ask the tow yard for the lot location and release rules so you can coordinate an inspection before repairs erase evidence.
Get checked by a clinician within 24 hours, even if symptoms feel mild. A rapid care visit creates a contemporaneous medical record tying pain to the crash and can reveal concussions or internal injuries that often show delayed symptoms. If you are unsure about next steps, many people seek a brief consultation with a local injury attorney, such as Buchanan, Williams & O’ Brien, P.C., to understand how Missouri’s rules on fault, statements, and medical billing may apply to their situation.
Week One: Notify Insurers Without Hurting Your Claim
Within a few days, notify your own carrier to open a claim number for collision, medical payments (MedPay), and potentially uninsured/underinsured motorist (UM/UIM) coverage. Report the date, time, location, vehicles, and police report number, but decline a recorded statement to the at-fault driver’s insurer until you have reviewed the police report and your medical status. A common mistake is signing broad medical authorizations that let an adjuster sift through unrelated records; instead, selectively provide crash-related records. Keep copies of your declarations page, correspondence, and every voicemail in a single folder or cloud drive so you can easily verify timelines and conversations.
Expect early calls from the at-fault insurer asking how you feel and offering a quick check for “medical inconvenience.” Accepting fast money can require a release of all bodily injury claims before you know the full extent of a soft tissue injury or the need for physical therapy. A simple way to buy time is to confirm that you are still evaluating your injuries and vehicle damage and will follow up once initial treatment stabilizes. Be polite, accurate, and brief. If asked for a statement, request the questions in writing or postpone until you can review the police narrative and your medical notes.
Preserving Evidence: EDR Data, Vehicle Parts, and Store Cameras
Modern vehicles store crash metrics in an event data recorder, including speed, braking, and seatbelt status in the seconds before impact. That data can be overwritten if the car is driven or if the battery is disconnected and later reconnected. If liability is contested, ask the tow yard to hold the vehicle without altering it, and send a spoliation letter by certified mail to the at-fault insurer and any custodians, asking them to preserve the EDR and key parts like the bumper cover, headlight assembly, and control modules. If a storefront camera may have captured the collision, visit or call the business quickly; many systems overwrite footage within 3 to 14 days.
Consider two common scenarios. First, a grocery store’s DVR auto-deletes after seven days; a same-week preservation request can secure the clip, while a late request means it is gone forever. Second, if someone starts a towed vehicle in the lot to move it, they can overwrite critical EDR entries; flagging the need to preserve data when you first call the yard can prevent that. Save all communications and mailing receipts, and photograph the vehicle in the lot before repairs. These steps add leverage when fault is disputed.
Tracking Damages: Medical Bills, Wage Loss, and Daily Impact
Build a paper trail that mirrors how adjusters evaluate damages. Keep every bill, receipt, and explanation of benefits for emergency care, imaging, prescriptions, and physical therapy. Note ICD-10 diagnosis codes and common CPT procedure codes on invoices, as they help confirm what treatment occurred and when. Ask your employer for a wage verification letter showing dates missed, hourly rate or salary, and overtime lost; if you are self-employed, gather invoices, 1099s, and calendar entries. A brief daily log documenting pain levels, sleep disruption, and tasks you cannot perform, like lifting groceries or driving on the highway, can substantiate non-economic losses when you later draft a demand letter.
Thirty Day Decision Points: Repairs, Treatment Plans, and Early Settlement Pressure
By week four, several trade-offs become clear. Approving repairs right away gets you back on the road, but replacing parts can eliminate proof of impact forces and crush patterns; when liability is disputed, ask the shop to photograph damage before disassembly and to retain replaced parts for inspection. Insurers may push for a quick global settlement that bundles property and injury claims; separating property damage from bodily injury lets you resolve the car claim while keeping medical issues open. Continue recommended follow-up visits; missed appointments appear in records and are often used to argue that injuries resolved earlier.
Keep your social media quiet about the crash and your injuries. A single photo of a family barbecue or a weekend errand can be mischaracterized to challenge your pain complaints. Confirm Missouri’s personal injury statute of limitations applies to your facts, and calendar interim dates like UM/UIM notice requirements or medical pay submission deadlines from your policy. If your condition stabilizes and your records are in order, you can assemble a demand package that includes the police report, photos, medical records and bills, proof of lost wages, and a concise liability analysis. If treatment is ongoing, continue documenting and reassess when you reach maximum medical improvement before valuing the claim.
These first 30 days are about controlling what you can: creating a clear medical record, preserving evidence that may vanish, and avoiding unforced errors that reduce case value. A steady cadence works best. Get care promptly, photograph and secure key physical details, notify insurers without giving recordings, keep organized files, and pause before signing broad releases or quick settlements. By day 30, you should have a claim number, a complete set of early medical documents, photo and video preservation underway, and a plan for either continued treatment or a well-supported demand when your condition plateaus.


Leave a Reply