
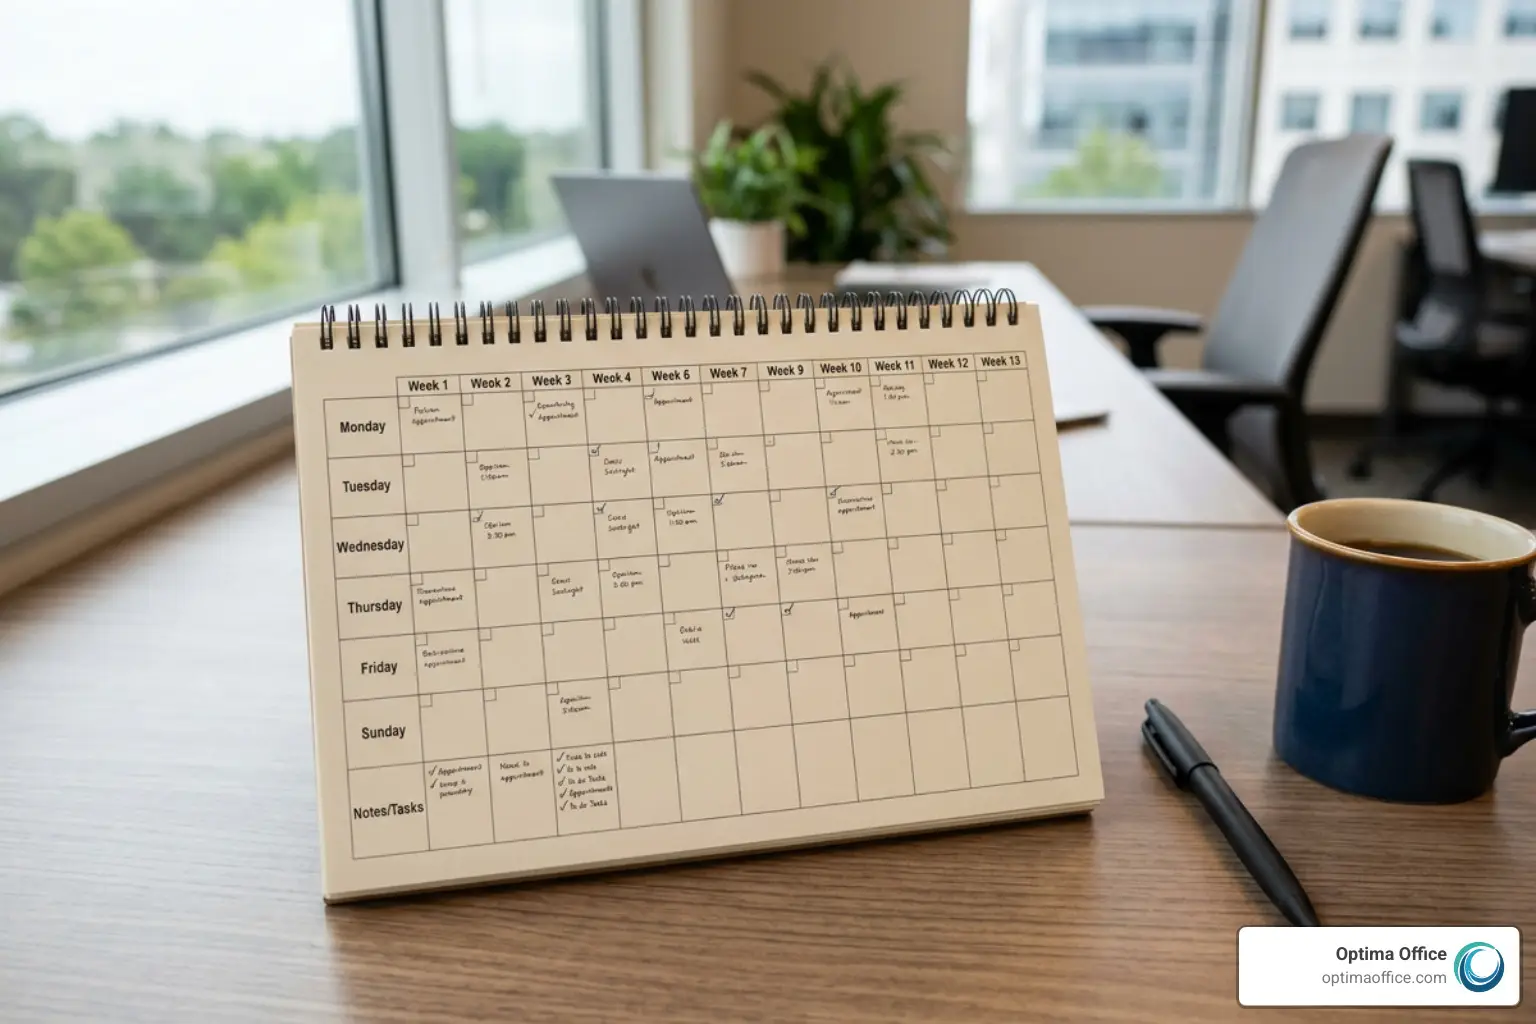
When lenders, vendors, and employees depend on timely payments, guessing your cash position is risky. A 13-week cash flow forecast gives owners and finance teams a practical, near-term view of receipts and disbursements, so decisions on payroll, vendor priorities, inventory buys, and covenant compliance are based on facts, not hope. This article explains a step-by-step method to set up a direct, weekly forecast you can maintain in a spreadsheet or finance tool. It covers what to include, where timing errors creep in, how to run scenarios, and what cadence keeps the model useful. Even if you already have a budget or monthly forecast, a 13-week view translates accrual plans into the actual bank balance that clears tomorrow morning.
-
Choose the 13-Week, Direct Method and Define the Goal.
Start with a direct method: list weekly inflows and outflows by category and roll to ending cash. Use 13 weeks because it spans one quarter, captures payroll cycles, tax remittances, and seasonality, and is short enough to forecast credibly. Build rows for customer receipts, credit card settlements, refunds, payroll runs, rent, debt service, insurance, taxes, inventory purchases, freight, and capital expenditures. Columns are weeks, with a running total: opening cash, net change, ending cash. Decide the purpose up front: avoiding a borrowing base breach, funding a product launch, or keeping minimum cash equal to at least one payroll. If you want expert help designing this structure or validating assumptions, some teams lean on PHG’s fractional CFO advisory services to accelerate setup and governance.
-
Pull Source Schedules and Convert Accruals into Cash Timing
Translate what sits in your accounting system into real timing. Begin with the A/R aging: apply expected collections using historical days sales outstanding, but adjust for customer behavior, marketplace holds, chargebacks, and credit card settlement lags. For high-volume e-commerce, include payment processor timing and reserve withholdings; for recurring invoices, map ACH batches and weekend bank delays. On the outflow side, extract the A/P schedule with vendor terms, early pay discounts, and any critical suppliers you must prioritize. Layer in the payroll calendar, including off cycle bonuses, 401(k) matches, and employer taxes. Add rent, insurance premiums, loan interest and principal, quarterly estimates, sales and use tax filings, and known renewals like software or maintenance contracts. If you import, do not forget freight surcharges and customs that can land before inventory is recognized as expense. Each item should land in the week cash actually leaves the bank.
-
Build the Weekly Model with Drivers, Controls, and Liquidity Levers
Structure the forecast so it ties back to operational drivers and reconciles to the bank. Receipts should be linked to a sales pipeline or shipment plan and adjusted for expected returns. Inventory purchases should reflect forecasted unit demand, lead times, and safety stock policies, not just a flat percentage of sales. Include fulfillment fees, shipping, and merchant discounts where they occur. Add checks: reconcile the model’s cash to actual bank balances each week, and foot weekly totals to monthly cash statements so the rollforward stays grounded. If you use a revolver, model borrowing base availability, certificate timing, and minimum liquidity covenants; schedule draws and repayments to maintain headroom. For capital projects, list deposits and stage payments across the weeks they will clear. The goal is a model simple enough to update quickly but detailed enough to explain variances.
-
Run Scenarios and Set Guardrails Before Pressure Builds
Stress-test the forecast so surprises show up on the page, not in the bank. Create downside cases for sales softness, DSO slipping by five days, a shipment delay that pushes receipts out, or ad spend cuts that also reduce near-term revenue. Set guardrails, such as minimum cash equal to two payrolls, covenant headroom thresholds, and caps on inventory before peak season proves out. For example, a direct-to-consumer brand facing higher return rates and card disputes can model a 2- to 3-week lag in net settlements and plan incremental collections outreach. A subcontractor can model retainage, draw approvals, and change order timing, then decide whether to delay a noncritical equipment purchase. Tradeoffs are explicit: stretching a few vendors by seven days might protect payroll but risks terms or supply; taking an early pay discount improves margin but tightens near-term liquidity.
Run a Weekly Cadence and Avoid Common Pitfalls
A forecast only works if you keep it current. Establish a weekly rhythm: by Monday, import bank activity, export A/R and A/P from your ERP, update actuals, and roll the view forward one week. Hold a 30-minute review where finance flags material variances by category, confirms drivers for the next four weeks, and updates the actions list. Share a one-page summary with owners, lenders, and the operations lead. Watch for mistakes that distort cash: mixing accrual and cash timing in the same line, omitting quarterly tax estimates, missing insurance installments, ignoring freight and duty that hit before inventory is received, and letting stale collection assumptions persist after a customer slows down. Document assumptions directly in the workbook and note any one-off obligations so the model stays auditable.
A solid 13-week cash forecast is less about a perfect spreadsheet and more about disciplined timing, clear ownership, and fast variance feedback. Start with a direct, weekly view, tie it to actual drivers, and keep it rolling so decisions happen before pressure spikes. Whether you maintain it in a spreadsheet or an FP&A platform, the principles are the same: put cash in the week it moves, reconcile to the bank, and test the plan against plausible bumps in the road. With that cadence in place, financing discussions, vendor negotiations, and staffing choices become deliberate steps rather than last-minute reactions.



Leave a Reply